Find an installer
Compare quotes from verified solar installers near you
Enter your PIN code & get matched on the next page.
Installers manually verified by a human
Sukhbir Agro (SAEL) an ambitions 5GW module and cell manufacturer has unsold solar panel inventory as per at REI 2025. As the ex Sales Director of Jinko Solar I can understand that its easier to for an Indian to become the mayor of new york than sell solar panels in a glutonous India solar market. Which is why many Top solar panel manufacturers India - are evaluating using www.pathtogreenhomes.com to reach out directly to 8000+ solar installers and Home Owners across 27,000 PIN CODES panel pan India. If you are panel / inverter/ battery sales ( he heart is with you) reach to Path To Green Homes here and write to them at [email protected]
India is barrelling toward a module glut—and, within 3–4 years, even a cell glut—regardless of today’s cell–module mismatch. Factories were sized for exports that aren’t materializing (thanks to shifting U.S. “Trump-era/Trump-style” duties and an EU market is dominated by ultra-cheap high quality Chinese supply where India panels have no place. Quality concerns are rising, and policy levers still reward capacity expanstion over credible performance like HALTS/CEC while BIS Star labelling of panels is wrong with basic calculation wrong. Panels are backed by useless BIS certification which is not done lot wise. Unless lot testing, finance, and subsidy design are re-tooled fast, homeowners and developers will feel the whiplash.
If you love someone (including yourself) and want safe, vetted panel picks, compare solar panels performing well in a Unbiased way by using the FILTER:
https://www.pathtogreenhomes.com/shop/solar-panels
a) How much overcapacity?
A buffet breakfast , A buffet lunch and A buffet dinner - in one day - all in all a revenge on food , because you think you paid the hotel too much.
-
Modules: India’s module capacity is set to exceed ~125 GW in 2025 vs ~15 GW domestic demand—implying a surplus and inventory pile-up.
-
Cells: While cell capacity has trailed modules; estimates show ~35 -45 GW cell capacity is expected online by 2027-2028 , a timeline much earlier than foreign media reports of 2030 Many foreign media are getting it consistancy wrong ( e.g. Wood Mackinzie) by saying India is structurally short on cells even as module lines mushroom because cell capacity is changing very fast. The author ( mmm myself) is involved on the ground to understand the psyche behind the upcoming cell lines. Is it time we reduce dependency on foreign consultants who are nixing up our carbon market , green hydrogen and pretty much most schemes. Net: Even with a strong installation year, India risks tens of gigawatts of idle module capacity and stranded inventory and piling debt.
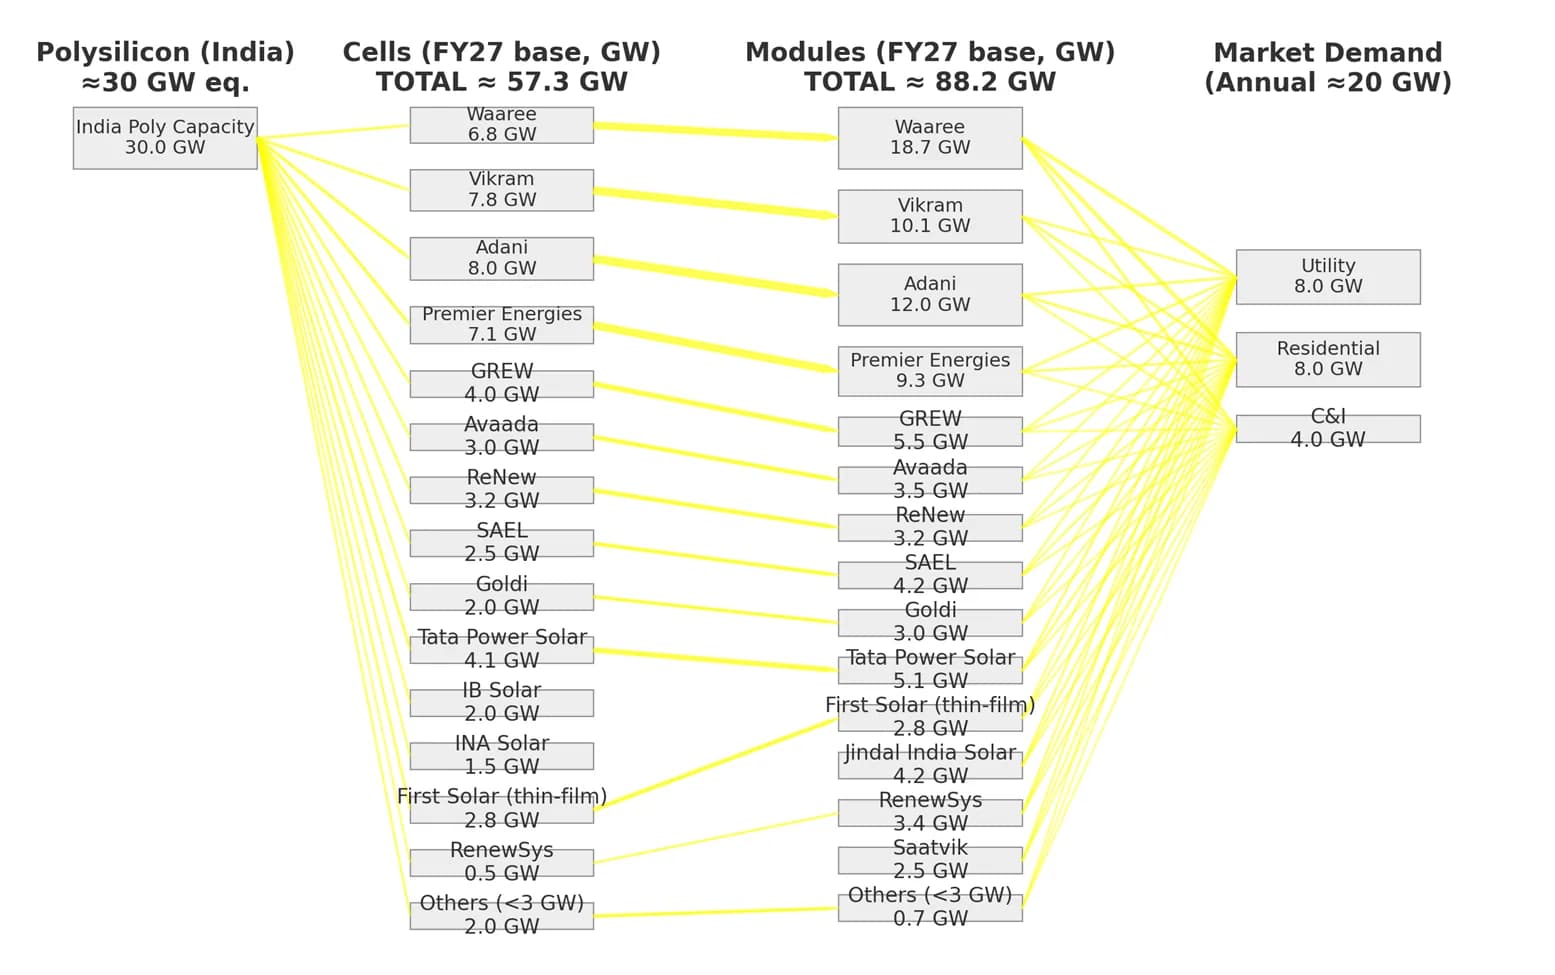
b) Who’s contributing to the glut?
- Gujratis : The laclusture performace in diamond - gems - jewels - machinery , dominated by Patel Gujratis of Surat , is making them get in solar panel and cell manufacturing. With ample cash with decades of profits , I blame them for oversimplification as I often hear them say " solar panel mein kya hai....Vivek bhai ? / What is the complexity in making a solar panel ?" There are no more than 1-2 good manufacturers in Gujarat who have good intention and long term vision. I know a former GM of Adani who used to make me wait for 5 hours for a sales meeting who has started 1GW solar manufacturing and scouting for OEM business. In 80s-2000' businesses shifted from Ahmedbad to Surat in textile -gems and diamond industries and 2025 is making in history for solar manufacturing for them. My meeting with a Surat businessman starts and end with the same same greeting " If any opportunity in RE lets discuss.....Vivek Bhai"
- Foreign Media agencies claim PLI-boosted build-outs from large corporates and mid-tier manufacturers racing to qualify nameplate capacity. Personally I think this is not a big reason since most the of cell lines which are coming up are not availing any PLI but are being built with own equity powered by a business case for 40% duty. Main driver now is the Policy-assisted import duties/ALMM dynamics that nudged rapid greenfield expansions
If you are a investor or a manufacturer planning on MAKE IN INDIA across poly-wafer- cell-and need ground information contact me at [email protected] We can make a slick report for you for your bank / investors , vetted by a reputed US based non for profit with on ground information. Information which only comes after being 2 decades in the India RE market and with a lot of hard work and feet and ears on the ground.
c) Exports: the miscalculation
-
U.S. exposure: India bet big on the U.S.; but new/raised U.S. trade actions have throttled that outlet, worsening India’s panel glut as simultaneously slow PPA signing in India by SECI SJVN etc has slowed market even resulting in cancellations , driven by greedy KUSUM etc developers wining at unsustainable prices who want to flip the project. Read my analysis here . While there is nothing wrong in fliping the projects , and I can help them sell projects at a premium of INR 2 lakh / MW , a good seller knows when to flip on time and not have endless tiring negotiations like Indias Trade negotiations with US which irritated Trump to punish us with high tariffs.
-
Bottomline : I have worked on the USAID project and know that despite Trump rheotic US manufacturing is self sufficiant.
-
EU reality: The EU market remains overwhelmingly Chinese-supplied—leaving little room for Indian modules to backfill.
-
Result: “Export-led decongestion” is not a near-term safety valve.
d) Cell manufacturing overcapacity—actually a mis-match
India’s risk is module overcapacity alongside cell over- supply. As the 2026 domestic-cell mandate kicks in, cells will have a short golden time for 1 year - leading quickly to ovecapacity
e) Quality slippages & cancellations
-
Defect rates: Developers behind closed doors have flagged and calcelled module deliveries from several Top 5 module manufacturers . Poor quality despite 30% margins in panel sales are unacceptable and show unwillingless to invest in quality.
-
European buyers’ caution: With EU sites saturated by Chinese supply and price wars, developers of European offices in India are extra strict; reports of rejections and schedule slippage have surfaced when QAP aren’t met
-
A specific “French developer cancelled " large panel order from Gujarat based panel manufacturer
f) BIS today: Paper in Motion
BIS certification is copy past of IEC standard while it ensures standards alignment—but type approval ≠ lot reliability.
Without lot-wise HALT-style stress screening and random market surveillance, poor batches will slip through. Pressure cooker test I employed in REC Singapore an help any developer get results quickly in 3 days without 3 months LOT testing. With backsheets out of the market Glass to Glass panels can reduce time to test significantly but we are still adhetring to old standards
g) The homeowner ride (what buyers experience)
-
Rock-bottom prices from oversupply—great on Day-1, but warranty solvency risk if weaker brands exit.
-
Spec confusion: TOPCon/“bifacial + glass-glass” labels mask spread in encapsulants, cell microcrack control, EL-testing rigor—affecting lifetime yield.
h) Who really gets the subsidy?
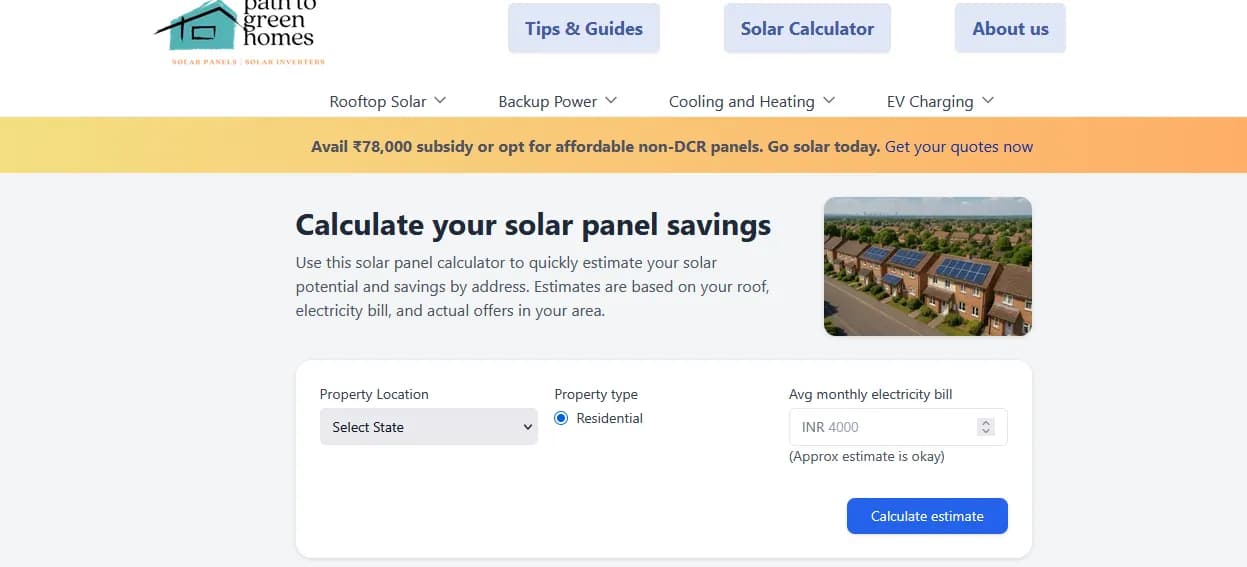
- PM Surya Ghar Yojana is paid to indirectly manufacturers since the HIGHER price of DCR panel eats the INR 78,000 subsidy while giving a sub product unless you have done th right selection.
https://www.pathtogreenhomes.com/solar-calculator-india
i) Debt in RE manufacturing is at record scale—who’s financing?
With retail investment sky rocket personally I suggest avoid any retail investor to invest in a Mutual find with names like , energy find , infra , energy opportunities , special opportunities , startup fund. Renewable has gone in a different league which is very tough to keep pace now.
| Manufacturer (listed) | Mutual fund scheme(s) seen holding | Note |
|---|---|---|
| Waaree Energies | Motilal Oswal Special Opportunities Fund (Reg/Direct), Motilal Oswal ELSS Tax Saver (Reg/Direct), Motilal Oswal Active Momentum (Reg/Direct) | Fund-wise % holdings shown on ETMoney’s shareholding page for Waaree (updated Nov 6, 2025). |
| Vikram Solar | HSBC Infrastructure Fund, UTI Value Fund, Tata Resources & Energy, Nippon India Power & Infra, Kotak Energy Opportunities, Kotak Manufacture in India, Franklin India Opportunities, Franklin India Small Cap, Bandhan Small Cap, Edelweiss Recently Listed IPO, Kotak Large & Midcap, Kotak Flexicap, Kotak Multi Asset, UTI Infrastructure (and others listed month-wise) | Trendlyne’s Monthly MF Holdings shows the exact schemes & share counts (Sep/Oct 2025). |
| Websol Energy Systems (cells/modules) | Motilal Oswal Nifty Microcap 250 Index Fund, Union Active Momentum Fund (plus tiny exposures via total-market/microcap index products) | Scheme names appear in Trendlyne/Kotak/Choice snapshots; many positions are small index/thematic weights. |
| Borosil Renewables (solar glass, upstream) | Angel One Nifty Total Market ETF (and other small index allocations over time) | MF activity is small and mixed month-to-month per Trendlyne. |
| Alpex Solar | Institutional (incl. MF) ownership rising; scheme-level visibility limited on free dashboards, but DIIs up to ~3.3% in Sep-25 | Use company/MF factsheets for named schemes; high-level DII/MF trend is visible |
| Insolation Energy (INA Solar) | DII/MF stake is small; specific schemes not prominently disclosed on free trackers | IREDA |